Saudi Conflict Hits Fiber Supply — Order Now to Lock Prices
Latest Market Update
The escalating conflict in Saudi Arabia and the wider Middle East is putting renewed pressure on the global chemical fiber and textile supply chain. With key shipping routes under threat, energy and raw material costs rising, and logistics uncertainty growing, buyers are increasingly focused on securing supply rather than waiting for prices to fall.
Now is not the time to wait for lower prices. It is the time to secure capacity, shipping space, and pricing.
Energy and Shipping Routes Under Pressure
The Strait of Hormuz and the Bab el-Mandeb route remain critical channels for global energy and trade. As the conflict expands, more vessels are being forced to reroute, extending voyage times and raising freight and insurance costs. War-risk premiums are rising, and shipping schedules are becoming less reliable.
This directly affects the chemical fiber chain. Crude oil uncertainty pushes up naphtha and other basic chemical feedstock costs, which then feed into PTA, MEG, polyester filament, nylon, spandex, and other synthetic fiber materials.
Raw Material Costs Keep Rising
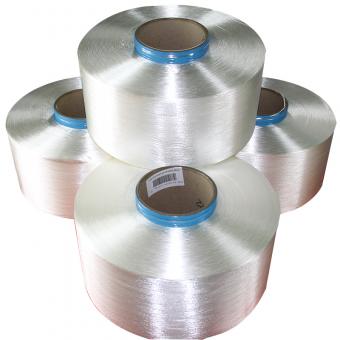
Cost pressure is moving quickly from upstream energy to downstream fiber and textile products. PTA and MEG prices continue to firm up. Polyester filament, nylon, and spandex are following the upward trend. Some international polyester fiber suppliers have already announced emergency price adjustments.
The upward momentum in raw materials has not shown a clear turning point. For downstream mills and buyers, procurement costs are becoming harder to control.
Logistics Disruption Extends Lead Times
Shipping disruptions in the Red Sea are adding a second layer of risk. Vessels rerouting around the Cape of Good Hope are facing longer transit times. Container freight, war-risk surcharges, and air freight costs have all moved higher. Some textile companies have already reported cargo delays and have paused new order acceptance.
For buyers with time-sensitive garment orders, logistics uncertainty is becoming even more challenging than price volatility.
Asian Plants Reduce Output as Capacity Tightens
High raw material costs and logistics disruptions are pushing Asian fiber and textile plants to reduce output. In major polyester textile hubs such as Surat in India, many weaving mills have cut production. In China, downstream weaving and dyeing enterprises are cautious about accepting new orders and are prioritizing old customers and price-locked contracts.
The industry is showing a clear divide: upstream costs remain firm, midstream production is shrinking, and downstream buyers are under pressure. As time goes on, capacity will become tighter and scheduling will become more difficult.
Market Outlook: Waiting May Cost More
In the short term, as long as the conflict continues, cost transmission will not stop. Garment retail prices face upward pressure, and some fast-fashion brands are already seeing higher production costs.
In the medium term, if the situation becomes prolonged, the global textile supply chain will undergo a real restructuring. Production regions that depend heavily on Middle East energy and raw materials may continue to shrink. Regions with more complete supply chains and stronger risk resistance may gain more orders.
Recommendation: Confirm Your Next Order Now
We recommend that customers confirm quantity, specification, and target delivery date as soon as possible, and prioritize locking current prices and production capacity.
The longer you wait, the more uncertain raw materials, freight, insurance, and lead times will become. In a worsening market, shortage and delay are real risks. Placing your order now is more stable than chasing goods later.
Contact us today for the latest quotation and price-lock options. We will prioritize your production scheduling.


 IPv6 network supported